Underwriting has always been one of those disciplines that not just decides the insurance premiums but also who gets covered. Today, AI is moving the needle from being pilot projects into the core of that decision-making. However, one question that truly lingers on today is whether manual underwriting will be gone in 2027, completely? This article will be diving deep into helping the insurers and the underwriters decode the answer to this question.
Why is manual underwriting under pressure?
The traditional underwriting significantly depends upon the experienced professionals reviewing the applications, interpreting the disclosures, pulling out third-party data, and applying the judgment that is shaped by years of portfolio experience. This works, but it does not scale well.
The underwriters in most organizations spend a large share of their time on administrative work; this includes re-keying data, chasing missing documents, and reconciling the information across disconnected systems. Additionally, submission volumes keep growing, and the brokers expect much faster growth followed by the way customers compare their options in minutes. This is a process that takes days and is becoming a competitive disadvantage.
This can be added to a shrinking pipeline.
A significant portion of the experienced underwriters are approaching retirement, and the industry is increasing.
What AI is already doing in underwriting?
AI is not about having a future promise here; instead, it’s about already embedding it in the underwriting workflows that are across personal, commercial, and specialty lines. However, the most mature use cases include:
Data extraction and submission intake
The AI models would be reading the broker emails, ACCORD forms, loss runs, and the supporting documents. They will then be structuring the data automatically. This alone will be removing hours of manual work per submission.
Enhanced risk assessment
The machine learning models will be analyzing far more variables than most of the traditional rating factors that allow this, including property imagery, telematics, IoT sensor data, public records, and the behavioral signals. The result of this is a more granular view of the risks for each applicant.
Triage and prioritization
The AI scores the incoming submissions by appetite fit and likelihood of binding so that the underwriters spend time on the risks that are most worth pursuing instead of working through queues that are in the arrival order.
Straight through processing
For simple, low-risk products, AI-driven systems will be able to quote and will be binding with no human touch at all. This is already quite common in areas such as basic personal lines and the small commercial policies.
Where AI still falls short
The replacement narrative is quite appealing, but it glosses over the real limitations. Thus, understanding them is quite essential for any realistic view of underwriting in 2027.
This includes:
Complex and unusual risks
The large commercial accounts, specialty lines, and novel exposures that include cyber, climate-related perils, or the emerging technologies often would be lacking the clean historical data that the AI models will be depending upon. Judgment, context, and negotiation still enormously matter here.
Explainability and regulation
The regulators and the court expect the insurers to explain why in particular the applicant was declined or priced in a certain way. The black-box models will be creating a compliance risk, especially as the rules around AI in insurance will be tightening across the jurisdictions. This includes fairness, bias, and proxy discrimination that remain few of the active concerns.
Data quality and bias
The AI will be reflecting the data that it learns from. If the historical underwriting decisions contained any gaps or bias, the models will be quietly reproducing them at scale. Additionally, governance, testing, and monitoring are quite optional.
Relationship and trust
In commercial insurance, underwriting is partly relational. The brokers and the clients value an underwriter who truly understands their business and can structure the creative solutions that will be standing behind a decision.
What underwriting will look like in 2027
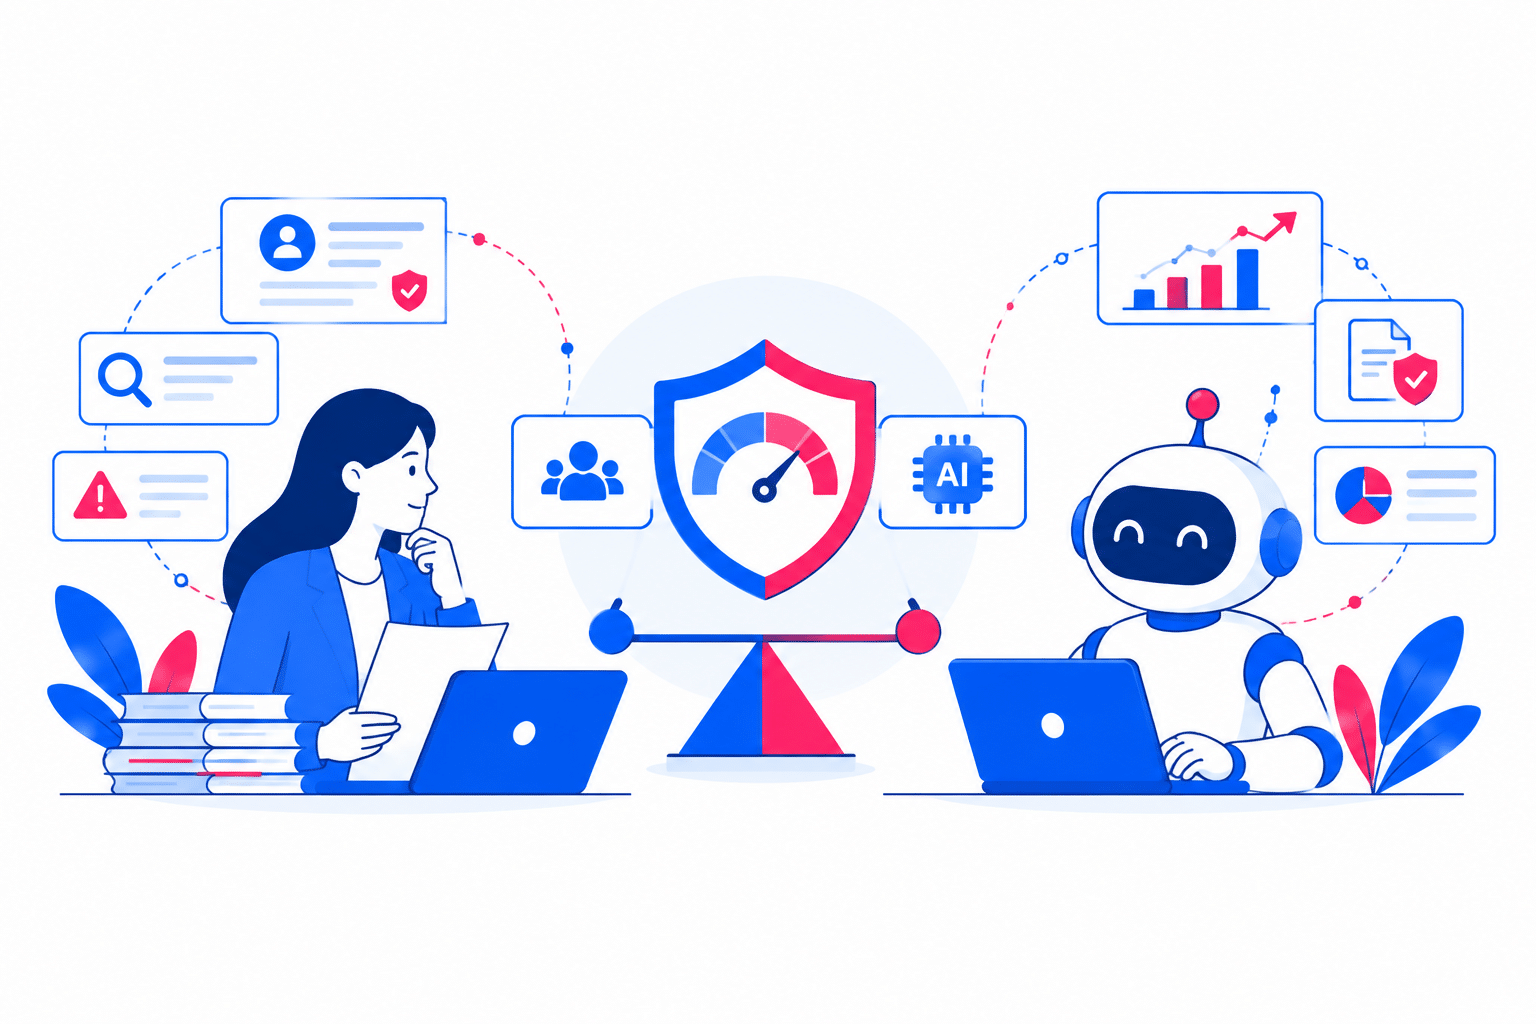
Underwriting will be changing in 2027, and the most accurate prediction is not replacement but instead redistribution. By 2027, aspects of underwriting will be significantly shifting and will be split into three broad lanes:
Fully automated lane
A simple, high-volume, well-understood risk is quoted and is bound by AI with human oversight that is focused on exceptions and audits.
AI-assisted lane
The majority of the mid-complexity risks. AI prepares the file, surfaces the insights, flags anomalies, and recommends a decision, while the underwriters review, adjust, and approve.
Expert-led lane
The complex, high-value, or unusual risks where human expertise leads and where the human expertise leads and AI plays an extremely important role in supporting analytical roles.
How can the insurers prepare
The carriers who want to benefit instead of react should be focusing on a few practical steps:
Fixing the data foundation first
AI gets only as good as the data feeding it. This includes having clean, connected data across policy, claims, and the external sources as the prerequisite for everything else.
Start the value is clearest
The submission intake and triage typically deliver quick and measurable returns with lower regulatory exposure instead of fully automated pricing decisions.
Building the governance early
It’s important to document how the models are trained, tested, and monitored and ensure decisions can be explained to regulators and customers.
Keeping the underwriters involved
The tools that are built with the underwriter input are adopted in a much faster time and perform better. It’s important to treat the experienced underwriters as co-designers and not obstacles.
Conclusion
AI will not be able to fully replace the manual risk assessment by 2027, and it will be changing underwriting permanently. The routine tasks will get automated, and the complex ones will get AI-assisted, and human expertise will concentrate where judgment truly matters the most