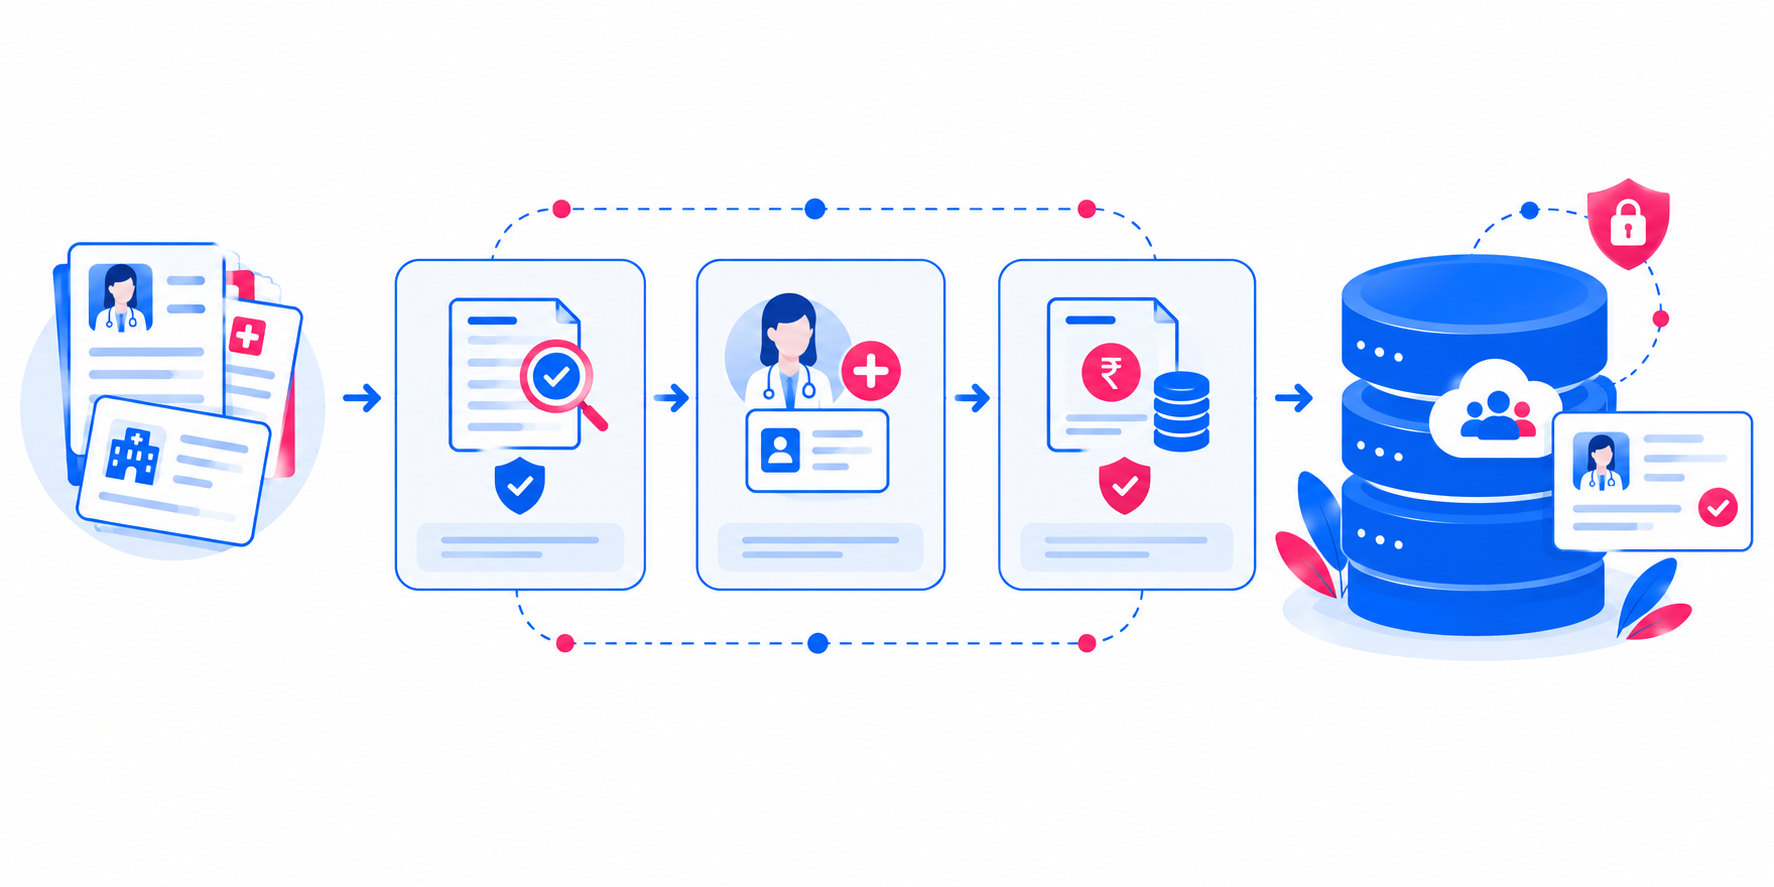
Most insurers aren’t asking whether to use AI anymore. They’re asking where to start and where it will actually pay off. The answer isn’t one big project. AI for insurance works best when it’s applied deliberately across the value chain, from the first customer conversation to the final claim payout, with each step building on the last.
Why a Value Chain View Matters
Many AI initiatives in insurance begin as isolated experiments: a chatbot here, a fraud model there. These pilots often show promise, then stall because they never connect to the broader operation. A value chain view fixes this by treating AI as a capability that touches every stage of the business: product design, distribution, underwriting, policy servicing, claims, and back-office operations.
Looking at it this way helps leaders spot where AI creates the most value, where the data already exists to support it, and how improvements in one area feed another. Better underwriting data, for instance, makes claims prediction sharper. Faster claims handling improves renewal rates. The gains compound when initiatives are connected rather than scattered.
Product Design and Distribution
The first stage of the chain is deciding what to sell and who to sell it to. AI helps insurers analyze customer behavior, market trends, and claims experience to identify unmet needs and design products that fit them more closely. Instead of relying on broad segments, insurers can use data to understand micro-segments and tailor coverage, pricing, and messaging accordingly.
On the distribution side, AI is improving how insurers reach and qualify customers. Recommendation engines suggest relevant coverage at the right moment, whether through an agent, a website, or an embedded insurance partner. Lead scoring helps agents focus their time on prospects most likely to convert. The result is distribution that feels more relevant to customers and more efficient for the insurer.
Underwriting and Risk Assessment
Underwriting is where AI for insurance has been adopted most readily, because the work is data-heavy and decision-driven. Machine learning models can process far more variables than traditional rating factors allow, including third-party data, property imagery, and behavioral signals, to produce more precise risk assessments.
The practical benefits are speed and consistency. Straightforward applications can be assessed and priced in seconds, while complex or borderline cases are routed to human underwriters with a clear summary of the factors driving the risk score. This is also where explainability matters. Regulators and policyholders expect to understand why a decision was made, so insurers need models whose reasoning can be traced and defended, not black boxes that simply output a number.
Policy Servicing and Customer Engagement
Once a policy is issued, AI shifts to supporting the ongoing relationship. Virtual assistants handle routine requests such as policy changes, document retrieval, and billing questions at any hour, reducing wait times and freeing service teams for conversations that need empathy or judgment. Natural language processing helps route inquiries to the right team and summarizes interaction history so customers don’t repeat themselves.
Beyond service, AI supports retention. Models can identify customers who may be at risk of lapsing and prompt timely outreach, or spot opportunities where a policyholder’s circumstances suggest a coverage gap. Done thoughtfully, this makes engagement feel helpful rather than pushy, which is what separates good use of AI from intrusive use of it.
Claims Handling and Fraud Detection
Claims is where policyholders judge an insurer most sharply and where AI delivers some of its most visible value. Automated intake, document extraction, and triage models can resolve simple claims in hours rather than days, while complex claims reach experienced adjusters with relevant information already organized. Image analysis can assess vehicle or property damage from photos, speeding up estimates considerably.
Fraud detection is the other major opportunity. AI can screen every claim for patterns associated with fraud, surface suspicious connections across claims, and prioritize cases for investigators. The key is calibration. Models should triage and inform human review rather than automatically denying claims, since over-flagging honest customers damages trust as much as missed fraud damages the loss ratio.
Operations, Compliance, and Back Office
The least glamorous part of the value chain is often where AI quietly saves the most effort. Document processing, data entry, reconciliation, and reporting all involve repetitive work that AI and automation handle well. In compliance, AI can monitor communications, flag potential regulatory issues, and help keep documentation consistent across regions and product lines.
These improvements rarely make headlines, but they free skilled staff from administrative tasks and reduce the errors that creep in with manual processes. For many insurers, back-office automation also funds and de-risks larger AI initiatives by delivering early, measurable returns.
Building the Foundations for Adoption
A strategic approach to AI for insurance depends on a few foundations that apply no matter which stage of the value chain an insurer starts with.
Data quality and access. AI is only as good as the data behind it. Insurers need clean, well-governed data that can be shared across functions, which often means addressing fragmented legacy systems first.
Governance and responsible use. Clear policies on fairness, explainability, privacy, and human oversight should be set before models reach production, not after problems appear.
Prioritized use cases. The best starting points combine meaningful business value with realistic feasibility. Quick wins build credibility and funding for more ambitious projects.
People and skills. Adoption succeeds when underwriters, adjusters, and agents understand and trust the tools. Training and change management matter as much as the technology itself.
Measuring What Matters
Finally, insurers should define success in business terms rather than technical ones. Useful measures include claims cycle time, loss ratio, underwriting turnaround, customer satisfaction, and cost per policy. Tracking these before and after each deployment shows which initiatives are working and where to invest next. Without this discipline, AI programs drift into activity without evidence of impact.
Conclusion
AI for insurance delivers the most when it’s treated as a strategy across the entire value chain, not a collection of disconnected pilots. Insurers that build strong data foundations, govern AI responsibly, and keep people in the loop will turn adoption into a lasting competitive advantage.